EMAPredictive2
Download script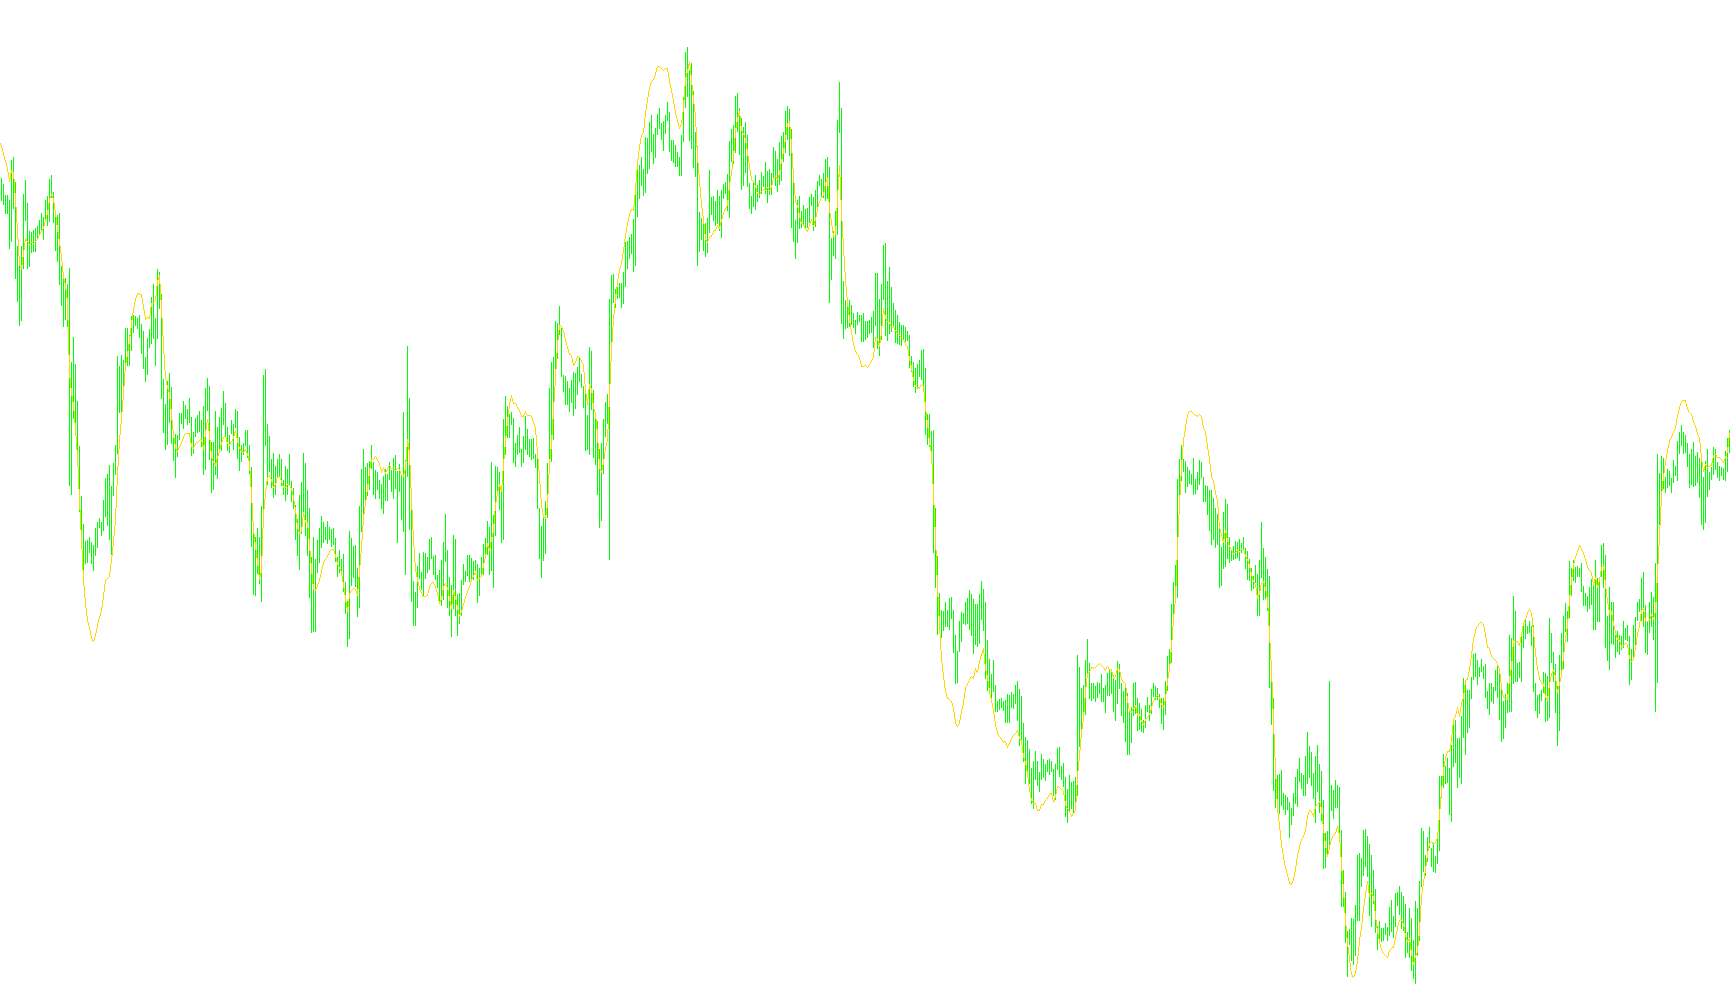
This tool is designed to provide a more proactive look at market trends by addressing a common limitation in traditional moving averages: the "time lag."
The Problem: Delayed Information
Standard moving averages are retrospective; they tell you what has happened in the past by smoothing out price data. In fast-moving markets, this often results in "lag," where the indicator shows you a trend only after it has already significantly progressed. For traders, relying solely on these smoothed prices can make it difficult to react quickly enough to current market conditions.
The Solution: Predictive Estimation
This script uses a mathematical approach to estimate where the price "is now" or where it is likely to be in the immediate future. It achieves this through three main components:
- Dual Moving Averages: The logic tracks two different Exponential Moving Averages (EMAs) simultaneously—one with a long period and one with a short period.
- The "Time Center" Logic: Every moving average has an effective window of time it represents. The script calculates the specific "center point" in time for both the long and short averages.
- Linear Extrapolation: By calculating the difference between these two moving averages relative to their respective center points, the script determines a trajectory (a slope). It then projects this path forward into the future based on a user-defined "Extra Time Forward" parameter.
How it Works in Practice
Instead of simply showing you a smoothed line of historical data, the indicator calculates a "predicted" value. It essentially asks: "Based on the relationship between the current short-term momentum and the long-term trend, where is the price heading next?"
Practical Application
This tool is particularly useful for identifying entry and exit points in crossover systems. Because it attempts to filter out market "noise" while reducing the delay inherent in standard averages, it can act as a more responsive "fast" indicator. Traders can use it to anticipate potential price movements rather than simply reacting to them after they have occurred.
//+------------------------------------------------------------------+
//|                                               EMAPredictive3.mq4 |
//|                                      Matthew ("Dr Chaos") Kennel |
//|                            ftp://lyapunov.ucsd.edu/pub/nonlinear |
//+------------------------------------------------------------------+
//
// Goal of this indicator:
//
//    Given three EMA's of varying lengths, use their values
//    for a estimator of "where we are now" or will be in the near future.
//    This is a very simplistic method, better ones are probably found
//    in the signal processing and target tracking literature.
//    A Kalman filter has been known since the 1950's 1960's and there
//    is better still.   Nevertheless this is easily programmable in the
//    typical environments of a retail trading application like Metatrader4.
//
// Method:
//
//     An an exponential moving average (EMA) or a simple moving average (SMA), for that
//     matter, have a bandwidth parameter 'L', the effective length of the window.  This
//     is in units of time or, really, inverse of frequency.  Higher L means a lower
//     frequency effect.
//
//     With a parameter L, the weighted time index of the EMA and SMA is (L-1)/2.  Example:
//     take an SMA of the previous 5 values:  -5 -4 -3 -2 -1 now.   The average "amount of time"
//     back in the past of the data which go in to the SMA is hence -3, or (L-1)/2.  Same applies
//     for an EMA.  The standard parameterization makes this correspondence between EMA
//     and SMA.
//
//     Therefore the idea here is to take two different EMA's, a longer, and
//     a shorter of lengths L1 and L2  (L2 <L1).     Now take the pairs:
//           [ -(L1-1)/2, EMA(L1) ]  [ -(L2-1)/2, EMA(L2) ]  which defines a line.
//
//
//     Extrapolate to [ExtraTimeForward, y], solve for y and that is the predictive EMA estimate.
//
// Application:
//     Traditional moving averages, as simple-minded linear filters, have significant group delay.
//     In engineering that isn't so important as nobody cares if your sound from your iPod is delayed
//     a few milliseconds after it is first processed.  But in markets, you can't
//     trade on the smoothed price, only the actual noisy, market price now.   Hence you
//     ought to estimate better.
//
//     This statistic (what math/science people call what technical analysts call an 'indicator')
//     may be useful as the "fast" moving average in a moving average crossover trading system.
//     It could also be useful for the slow moving average as well.
//
//     For instance, on a 5 minute chart:
//
//       try for the fast: (will be very wiggly, note)
//
//                           LongPeriod 25.0
//                           ShortPeriod 8.0
//                           ExtraTimeForward 1.0
//
//       and for the slow:
//
//                           LongPeriod 500.0
//                           ShortPeriod 50.0 to 200.0
//                           ExtraTimeForward 0.0
//
//  But often a regular MA for the slow can work as well or better, it appears from visual inspection.
//
//  Enjoy.
//
//  In chaos there is order, and in that order there is chaos and order inside again.
//
//  Then, surrounding everything, pointy haired bosses.
//
#property copyright "Matthew (Dr Chaos) Kennel"
#property link      "ftp://lyapunov.ucsd.edu/pub/nonlinear" // my academic software site.  No finance.

#property indicator_chart_window
#property indicator_buffers 1

#property indicator_color1 Red
//---- input parameters
extern double       LongPeriod=25.0;  // note that for an EMA you can have floating point numbers.
extern double       ShortPeriod=8.0;
extern double       ExtraTimeForward=1.0; // how much to further extrapolate location.

//---- buffers
//---- indicator buffers
double ExtBuffer[];

//+------------------------------------------------------------------+
//| Custom indicator initialization function                         |
//+------------------------------------------------------------------+
int init()
  {

   SetIndexBuffer(0,ExtBuffer);
 //---- drawing settings
   SetIndexStyle(0,DRAW_LINE);
//---- initialization done
   return(0);
  }


int start()
  {
   int limit;
   int counted_bars=IndicatorCounted();
   double ma1,ma3;
   double p1,p3;
   double t1,t3,t;

//---- check for possible errors
   if(counted_bars<0) return(-1);
//---- last counted bar will be recounted
   if(counted_bars>0) counted_bars--;
   limit=Bars-counted_bars;

//---- main loop
   p1 = 2.0/(LongPeriod+1.0);
   p3 = 2.0/(ShortPeriod+1.0);

   t1 = (LongPeriod-1.0)/2.0;
   t3 = (ShortPeriod-1.0)/2.0;
   t = ShortPeriod + ExtraTimeForward;

   ma1 = Close[limit-1];
   ma3 = ma1;
   for(int i=limit-1; i>= 0; i--) {
      //---- ma_shift set to 0 because SetIndexShift called abowe
      double val = Close[i];
      double slope1, predict;


      ma1 = p1*val + (1.0-p1)*ma1;
      ma3 = p3*val + (1.0-p3)*ma3;

      slope1 = (ma3-ma1)/(t1-t3);

      predict = ma3 + slope1*t;

      ExtBuffer[i]=predict;
  }
//---- done
   return(0);
}
//+------------------------------------------------------------------+
Comments